


By:
Jonathan Street
CEO, Thinktank
The year is 2006. John Howard is prime minister, Twitter has just launched, Shakira’s Hips don’t lie is topping the charts and the Socceroos are steaming into the knockout stages of the World Cup.
You pull out your BlackBerry phone and read that a new lender called Thinktank is entering Australia’s mortgage market.
Two decades later, Australia’s lending landscape looks very different. The industry has undergone a global financial crisis, a pandemic and a major digital shift, transforming the role of the broker and the needs of borrowers along the way.
Thinktank has evolved alongside that changing landscape, expanding beyond its commercial property lending roots to meet the demands of a specialist lending market that never has, and never will, stand still.
Its 20-year history also reflects a broader shift in the third-party channel, as brokers work across a wider range of borrower needs and increasingly complex financial arrangements.
To mark Thinktank’s anniversary, we sat down with CEO Jonathan Street to reflect on the lender’s journey, its place in today’s lending landscape and what the next chapter might hold.
Thinktank’s 20-year journey has unfolded alongside a lending market that has changed considerably since the business first opened its doors in 2006, with the original intention to address a gap in the commercial lending market.
“We saw an opportunity to bring a longer-term, set-and-forget commercial lending proposition to brokers and their clients, backed by people who genuinely understood commercial credit,” says Street.
“The opportunity was about much more than product, however. We wanted to build a specialist broker-oriented lender centred around experienced people who were prepared to understand the borrower, the property and the circumstances behind each transaction, rather than simply applying a rigid credit framework.”
From the outset, Thinktank operated exclusively through the broker channel.
“We offered full upfront and trail commissions, which was significantly differentiated at the time and reflected our belief in the important role brokers could play in commercial finance,” Street says.
“We saw an opportunity to bring a longer-term, set-and-forget commercial lending proposition to brokers and their clients, backed by people who genuinely understood commercial credit.”
- Jonathan Street
“Like any new lender entering the market though, establishing brand, identity and credibility took time. That meant striving to be consistent in our credit decisions, doing what we said we would do and openly exchanging knowledge and experience with brokers as we built the business.
“Those early principles established the foundations for Thinktank: specialist and complex lending expertise, sound credit, building broker relationships and a willingness to share what we knew along the way. Twenty years later, they still remain fundamental to the business.”
But Australia’s credit market doesn’t stand still.
To thrive in specialist lending, Thinktank had to adapt to evolving markets, changing regulation and shifting borrower structures, developing solutions that meet brokers’ and borrowers’ needs while anticipating where those needs might go next.
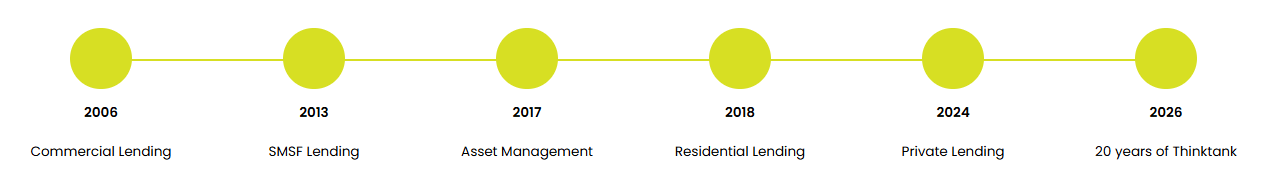
Soon after the Global Financial Crisis, Thinktank began to broaden its reach.
It first expanded beyond commercial property lending in 2013, when it introduced self-managed super fund (SMSF) products. Residential lending followed in 2018, then construction in 2023 and private lending in 2024.
“What has not changed is the importance of experience and good judgement,” Street adds.
“Particularly in commercial and complex lending, it remains necessary to understand the borrower, the property, the ownership structure and what actually matters in that particular set of circumstances.”
As a lender inextricably linked to the broker channel from the outset, much of Thinktank’s evolution over the past two decades has reflected that of the industry itself.
“Twenty years ago, the role of the mortgage broker was much more heavily associated with residential home lending,” Street says.
“Today, brokers play a far broader role in supporting their clients. They are increasingly working with self-employed borrowers, business owners and property investors, extending to construction, development, unsecured, cash flow, vehicle, equipment and a range of more complex lending requirements.
“This evolution has been important to Thinktank because, in many respects, we have grown alongside it. As brokers have broadened their capability and their clients’ needs have become more sophisticated, we have expanded our own proposition to support them.”
That broader role has also changed the relationship between brokers and specialist lenders, particularly when transactions involve complex ownership structures or commercial finance.
“A broker does not necessarily need to arrive with every aspect of a commercial or SMSF transaction resolved,” Street says.
“Our role is to bring our experience to the conversation early, work through the structure with them and help identify a practical path for the client in a complementary way.”
The opportunity presented to brokers by the specialist lending space has become increasingly difficult to ignore.
According to the Australian Bureau of Statistics, more than 20 per cent of Australian adults now receive their primary income from non-salary sources, while more than 50 per cent draw income from multiple non-salary streams.
“Self-employed borrowers, companies and trusts, SMSFs and more sophisticated ownership structures are no longer fringe parts of the lending market,” Street says.
“These are now common circumstances that brokers encounter every day.
“Increasingly, the value of a specialist lender extends beyond providing a particular product. It includes helping brokers strategically assess how a transaction may be structured, what information is required and navigating a clear and achievable pathway to an optimal outcome.”
“Self-employed borrowers, companies and trusts, SMSFs and more sophisticated ownership structures are no longer fringe parts of the lending market.”
- Jonathan Street
Despite the expansion, Street says Thinktank’s core proposition has remained centred on broker distribution and complex lending.
“We continue to place considerable importance on sound credit, experienced people, sharing knowledge and taking the time to understand the circumstances behind a transaction,” Street adds.
“What has changed considerably is the scale and breadth of the capability surrounding those fundamentals.”
The business has also grown significantly in scale.
In its 20th year, Thinktank reached $10 billion in assets under management and had funded more than $20 billion in residential and commercial property loans.

Exclusively Broker, Simplifying Complexity, Uncommon Expertise
FY2025–26 settlements totalled $5.2 billion, up 41 per cent year on year, while Thinktank’s workforce has grown to more than 210 people.
“We have benefited enormously from the combined strength, depth and stability of our expanded leadership team over more recent years in dynamically shaping the business, developing our people and building out the capabilities and relationships that underpin who we are today and where we will be tomorrow,” Street says.
For brokers looking to grow their commercial lending business, Street also points to opportunities among existing clients who own businesses or invest in property.
“Many existing clients own businesses, invest in commercial property or may wish to acquire their own business premises, while broker participation in commercial lending has been rising yet remains considerably lower than in residential,” he says.
“Borrowers are also not necessarily refinancing simply to achieve a lower rate. They may be seeking to improve cash flow, release equity for further investment, consolidate facilities or restructure debt to support the next stage of a business or investment strategy.
“Changes to tax and ownership settings are also likely to generate further conversations.”
Looking to Thinktank’s next decade, Street expects technology to streamline lending processes while borrowers’ financial circumstances continue to grow more complex.
“Technology and AI should continue to remove friction from the process, improve the way information moves between brokers, borrowers and lenders, and make specialist expertise more readily accessible,” he says.
“At the same time, particularly among self-employed and SME borrowers, financial circumstances are unlikely to become any easier to manage. Changes in regulation and tax policy, different income sources, ownership structures and increasingly sophisticated investment strategies will continue to generate scenarios that require more than a standard lending solution approach.
“That represents a significant opportunity for brokers.”
For Thinktank, Street says the aim is to use technology to strengthen its specialist lending proposition without losing sight of the principles that have underpinned the business for 20 years.
“Technology and AI should continue to remove friction from the process, improve the way information moves between brokers, borrowers and lenders, and make specialist expertise more readily accessible.”
- Jonathan Street
“We are also continuing to evolve our products and policies in response to what we are hearing from brokers,” Street says.
“Being exclusively broker introduced gives us a very direct connection to the market and broker feedback has always played an important role in how we develop the business.
“We expect Thinktank in 2046 to look considerably different in scale and capability to the business today.
“What we would hope remains recognisable are the fundamentals: specialist expertise, sound credit judgement, strong relationships, a willingness to understand the circumstances behind a transaction and a residing commitment to the broker channel.”
Jonathan Street
CEO, Thinktank


