

 iscover


The Australian Finance Industry Association’s (AFIA) Finance Industry Code of Practice took effect on 1 October, bringing non-bank and specialist lenders, buy now, pay later (BNPL) providers and motor finance businesses under a single framework.
Having been established in practice in September 2025, the code sets out standards for participating providers across a range of consumer and small business finance products, covering areas including customer communication, financial hardship, fraud prevention, the use of AI and dispute resolution.
Its launch follows a transition period during which members have been able to align their systems, policies and practices with the new standards.
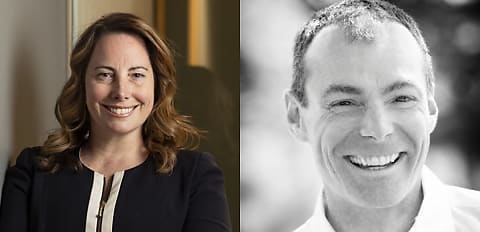
AFIA CEO Diane Tate said the code marked an important moment for the finance industry after years of work.
“Today, commitment becomes practice. Non-bank and specialist lenders are stepping forward, making themselves publicly accountable and demonstrating their determination to deliver stronger protections and better outcomes for the millions of Australians they serve,” she said.
“At a time of heightened global and economic uncertainty, persistent cost pressures and accelerating technological change, Australians need confidence in the financial system and the organisations they rely on for finance.
“That confidence cannot be taken for granted. It is earned through clear standards, responsible decisions and consistent conduct, particularly when customers are under pressure or circumstances are difficult.”
What does the code do?

The code sets out clear standards for how participating finance providers should communicate with and support customers, with AFIA outlining key areas in which consumers are expected to benefit.
These include:
- Customer-focused conduct: Clear standards of conduct and disclosure intended to ensure AFIA members put customers first and support good customer and industry outcomes.
- Clear communication and transparency: Simple, customer-friendly information about products, terms and fees.
- Scam and fraud protection: Clear rules covering scam prevention, information and data protection, and privacy and security measures.
- Responsible use of technology and AI: Safeguards intended to ensure innovation is balanced with customer protections.
- Support during financial difficulty: Stronger obligations to assist customers experiencing financial hardship or vulnerability, including small businesses facing financial difficulties. Members also commit to helping prevent the misuse of products to inflict harm on another person.
- Access to dispute resolution: Prompt and efficient complaint handling, with access to external dispute resolution mechanisms when complaints cannot be resolved directly with a finance provider.
The code is intended to provide a consistent set of expectations across a diverse range of finance products, while allowing the industry to continue to innovate.
Ms Tate said the framework reflected a decision by the non-bank finance industry to take a more active role in setting and demonstrating its standards.
“Leadership is not simply describing what we believe. It is demonstrating what we are prepared to do, being accountable for the decisions we make and continuing to improve as circumstances change.
“The AFIA Code makes that commitment visible. It establishes a clear benchmark for responsible finance, bringing stronger protections and greater accountability together with competition and innovation. Importantly, it provides a framework that will continue to evolve as customer expectations, technologies and risks change, while keeping good customer outcomes at its centre.
“By publicly committing to these standards, AFIA Code signatories are helping strengthen confidence not only in their own organisations, but in Australia's broader financial system at a time when that confidence matters more than ever.”
Independent monitoring and compliance
The code is independently monitored by the Finance Industry Code Compliance Committee (FICCC), which is responsible for assessing applications, monitoring compliance and investigating alleged breaches.
FICCC independent chair Tim Grimwade congratulated AFIA and its members on the commencement of the code, saying the committee had an important role in overseeing compliance.
“AFIA has tasked the FICCC with an important oversight and monitoring role in relation to code compliance, and we look forward to working with AFIA Code members in improving standards across the industry and providing better outcomes for customers,” Grimwade said.
He also encouraged other finance providers to sign up to the framework.
“Non-bank lenders and other finance industry participants that are serious about playing their part in building trust, transparency and fairness in the industry need to join the AFIA Code to demonstrate that commitment to their customers.”
The rise of the non-bank
The introduction of the AFIA code comes as non-bank lenders continue to expand their presence in Australia’s credit market.
RedZed was the most recent lender to join the framework, other non-bank lenders to have joined the code include Bluestone, Angle Finance, Auto Finance, Prospa, MoneyMe, Resimac, Shift, NOW Finance, and Pepper Money, which became the first organisation to complete accreditation in February.
According to Australian Bureau of Statistics (ABS) Lending Indicators, the value of new home loans written by non-bank lenders rose 65.2 per cent year on year to $10.49 billion in the June 2026 quarter.
By comparison, lending by major banks and other ADIs increased by just 2.6 per cent to $87.61 billion over the same period.
Non-banks now account for 10.7 per cent of new home lending by value, up from 4.8 per cent when the ABS series began in 2019.
That growing market share is also reflected in the lending volumes and performance reported by the industry itself. AFIA’s inaugural Residential Mortgage Non-Bank Lenders (RNBL) report, published in December 2025, found that non-bank lenders helped 51,000 Australians purchase a home during the 2025 financial year, with surveyed AFIA members providing $72.2 billion in home loans.
The report also found that early-stage arrears among non-bank lenders remained relatively low, at 0.67 per cent compared with 0.58 per cent for major banks, while 90-plus-day arrears were lower for non-banks, at 0.81 per cent versus 1.10 per cent for major banks. More than 80 per cent of hardship applications received by residential mortgage non-bank lenders were approved.
Tate said the code was intended to be an ongoing commitment rather than a one-off compliance exercise, with members expected to respond to emerging risks and changing customer expectations.
“Good regulation provides an essential foundation, but responsible industries must be prepared to go further. They must anticipate emerging risks, listen to customers and the community, and lift their standards to evolve.
“The AFIA Code is industry leadership in action. It is not a once-off compliance exercise. It is an enduring framework through which members will be expected to learn, adapt and demonstrate how their businesses support good customer outcomes.”
[Related: Brokers call for ‘level playing field’ as ASIC probes lender oversight]
 Want to see more stories from trusted news sources?
Make Broker Daily a preferred news source on Google.
